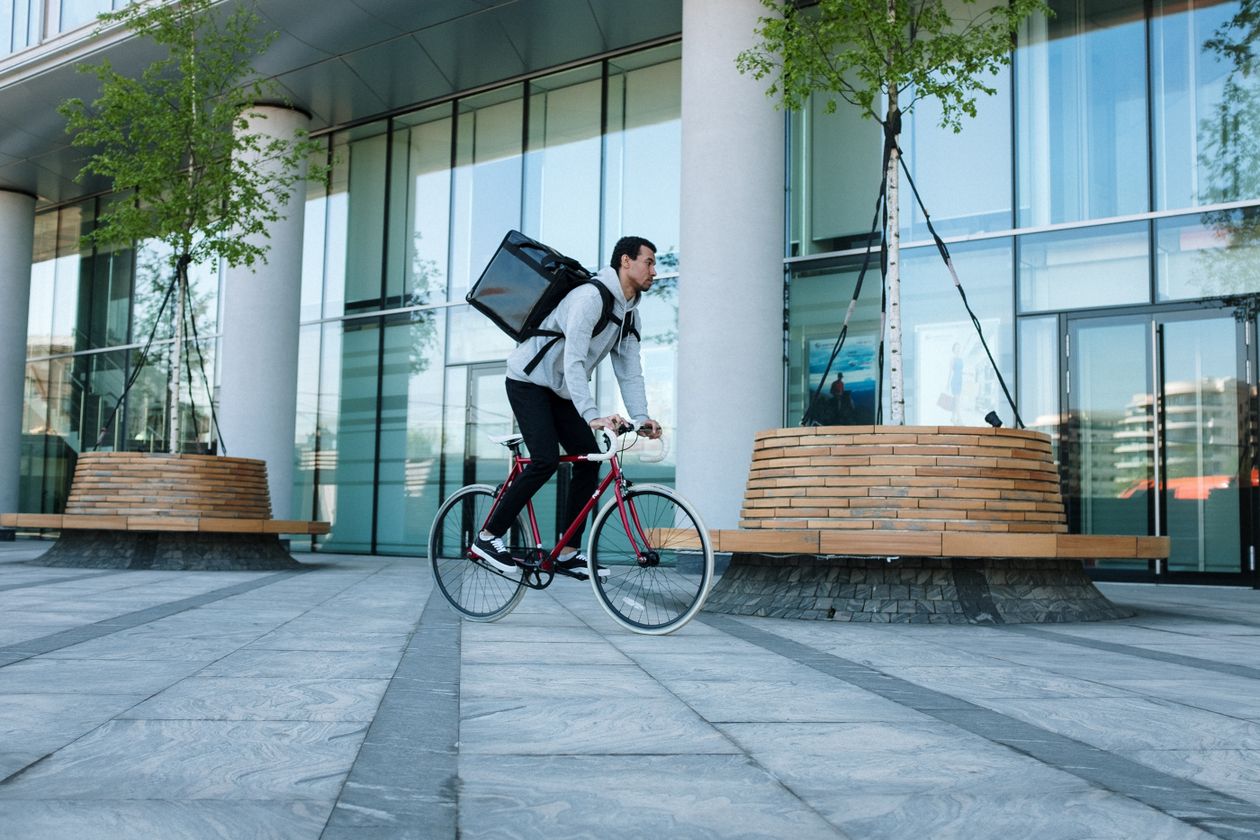
A delivery e-bike charges behind the counter of a Dartmouth restaurant overnight. A cordless drill battery sits in a job site trailer in Burnside. A forklift tops up at a loading dock in Bedford. All of it runs on lithium-ion batteries, and Halifax Regional Fire & Emergency built this year’s Fire Prevention Week around warning people about exactly that. Here’s the short answer on lithium-ion battery fire insurance: a fire is still a fire. Your commercial property policy generally covers it the same way it covers any other fire, as long as nothing in your actual wording says otherwise.

Why Lithium-Ion Batteries Are Suddenly a Fire Department Priority
Lithium-ion batteries run almost everything rechargeable in a modern business: phones, laptops, point-of-sale devices, power tools, e-bikes, scooters, forklifts. Fire Prevention Week kicked off in early October with Halifax Regional Fire & Emergency putting battery safety front and centre, and the department’s own safety guidance is direct about why. A lithium-ion battery that’s been damaged, charged the wrong way, or paired with the wrong charger doesn’t just stop working. It can overheat, catch fire, or in the worst case, explode. These fires move fast and the smoke they give off is especially toxic. Halifax Regional Fire & Emergency says fire departments are seeing more fires linked to these batteries every year, not fewer.
Does Your Commercial Insurance Actually Cover a Lithium-Ion Battery Fire?
The Insurance Bureau of Canada puts it plainly for homeowners: fire is covered by insurance, as long as nobody started it on purpose. The same principle carries over to a commercial policy. Insurers treat a battery-caused fire as a fire loss, not as some separate category that gets singled out and excluded. That means your commercial property coverage generally responds the same way it would to a fire that started from a space heater or faulty wiring. Business interruption insurance, the part of a commercial policy that replaces income you lose while you can’t operate after a covered loss, works the same way.
What actually changes is the liability side. The Insurance Bureau of Canada’s own guidance notes that a battery fire can leave you liable for damage to a building or units beyond your own, a point that applies just as much to a commercial tenant as it does to a homeowner in a condo. The bureau also flags e-bikes and e-scooters specifically, saying they may need coverage beyond a standard policy. If your business owns or leases e-bikes for deliveries, or you’re a landlord letting tenants charge them on site, that’s a direct question for your broker rather than an assumption either way.
Where This Actually Shows Up in a Halifax Business
Does a Delivery E-Bike or a Cordless Drill Count?
Yes, and that’s the part most policies were never written with in mind. A restaurant running its own delivery service has e-bike batteries charging on site most nights, often in the same back hallway Halifax Fire specifically warns against charging near. A contractor’s job site trailer is full of cordless drill, saw and grinder batteries, usually plugged into the same outlet strip at the end of every day. A trucking or warehouse operation runs forklifts and pallet jacks off charging stations that sit in use for hours at a stretch. A commercial landlord renting space to any of them is often the one deciding whether tenants can charge an e-bike in a stairwell at all.

A note from working across HRM: this risk looks different from one end of the municipality to the other, a Burnside contractor charging tool batteries off a job trailer, a Dartmouth kitchen running its own delivery e-bikes, a downtown shop with a wall of chargers behind the till. None of it is unusual, and none of it needs a different policy. It needs one that was actually built with it in mind.
What To Actually Do About Battery Risk at Your Business
- Set up one charging area away from exits, hallways and anything flammable, and keep spare batteries there instead of scattered around a till or a tool bag.
- Charge devices on a flat, hard surface, never on a mattress or couch, and unplug them once they’re full instead of leaving them charging overnight.
- Replace a lost or worn charger with the manufacturer’s own, or an approved equivalent, rather than whatever cord happens to be lying around the shop.
- Watch for a battery that’s swelling, leaking, smells unusual, or runs hot while charging, and pull it from service the moment you see it.
- Take damaged or worn-out batteries to an approved recycling drop-off instead of the garbage or the blue bag. Halifax Fire’s own guidance says doing that can start fires in garbage trucks and recycling facilities, which is exactly why there’s a separate process for them.
- Ask your broker whether your property and business interruption limits still make sense now that your business is running more battery-powered equipment than it was five years ago.
The Bottom Line
A lithium-ion battery fire isn’t a new category of loss that your policy has to specifically name before it responds. It’s a fire, and commercial property and business interruption coverage generally treat it the way they treat any other one. What’s actually changing is how often this kind of fire is starting, and where in a business it’s most likely to start. Halifax Fire is telling business owners the same thing it tells homeowners: store batteries properly, charge them safely, and get rid of the damaged ones the right way. The insurance side of this is already in place. The risk management side is still mostly up to you.
I’m Rayanur Rahman, a commercial insurance broker with Western Financial Group in Bedford, Nova Scotia. When you call my office, you reach me directly, not a call centre and not a general line, so questions like this one get a straight answer instead of a form to fill out.
Running More Battery-Powered Equipment Than You Used To?
If charging stations, e-bikes or cordless tools have become part of how your business runs, I’ll check that your property and liability coverage actually kept up with it.
Sources: Halifax Regional Fire & Emergency, “Lithium-Ion Battery Safety” Fire Prevention Week 2026 info sheet (halifax.ca); Insurance Bureau of Canada, “A Growing Fire Risk in Plain Sight” (ibc.ca). Photo of delivery courier by cottonbro studio on Pexels. Photo of workbench by Chris Briggs on Unsplash. General information only, not advice on your specific policy. Check your own wording.
Leave a Reply